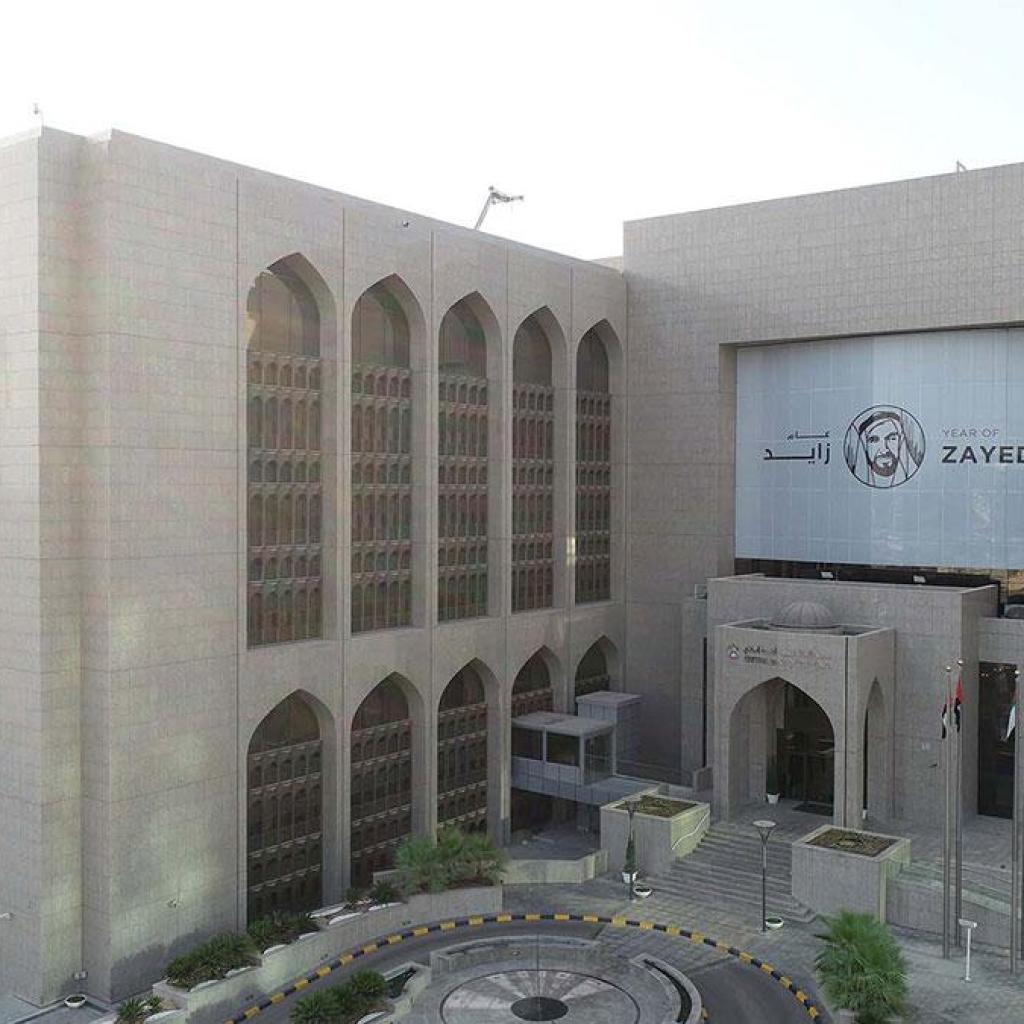
Dubai, UAE: In a landmark move, the Central Bank of the UAE (CBUAE) has abolished the long-standing minimum salary requirement for personal loans. Under the new directive, banks will no longer apply a blanket floor — previously around AED 5,000 — and will instead define their own eligibility criteria.
This shift aims to significantly enhance financial inclusion, particularly for low-income workers, younger residents, and blue-collar labourers. With the change, more people can now open bank accounts and access regulated credit in a safer and more formal way.
What’s Changing & Why It Matters
Abolishing the AED 5,000 Threshold
For years, many banks in the UAE required borrowers to have a minimum monthly salary of AED 5,000 to qualify for personal loans. That barrier has now been removed, and financial institutions have been given the freedom to set their own salary rules internally, based on their risk assessment.
Greater Access to Banking
The Central Bank’s directive is expected to open doors for lower-wage earners who may have found it difficult to meet previous lending criteria. These individuals will now be able to access “cash on demand” and other personal financing options.
Integration With the WPS
The change is closely tied to the UAE’s Wage Protection System (WPS). Under the WPS, salaries are deposited into regulated accounts, which now can be used more effectively: banks can automatically deduct loan instalments when wages land in these accounts, making repayment more reliable and structured.
Implications for Different Segments
For Low-Income and Blue-Collar Workers
This group stands to benefit the most. Previously, low-income workers might have been excluded from credit markets, but the new policy gives them greater access to formal credit channels. This move could help reduce reliance on informal or potentially risky lending sources.
For Young Residents and First-Time Borrowers
Young professionals or residents just starting their careers often have lower salaries. By removing the rigid threshold, the central bank is enabling them to build credit history earlier, and potentially secure better financial products in the long run.
For Banks
Lenders now have more flexibility, but also greater responsibility. While they can lower barriers, they must carefully assess risk, since some borrowers may have lower or more variable incomes. This may prompt more sophisticated internal credit models.
Why the Central Bank Did It
Financial Inclusion Push
The central bank has framed this reform as a key part of its broader financial inclusion strategy. By making credit more accessible, the UAE aims to ensure more of its resident population participates in the formal banking system.
Encouraging Responsible Lending
Linked with the WPS, the new approach supports automatic salary-based instalment deductions, reducing the risk of loan default. The system also encourages banks to lend responsibly by assessing credit risk on a case-by-case basis.
Aligning with Regulatory Goals
This move aligns with global and regional trends where central banks are encouraging financial systems to be more inclusive, especially for underserved sections of the population.
Potential Challenges & Considerations
- Risk Management: Banks will need to develop more nuanced lending criteria to handle borrowers with lower or unstable salaries.
- Repayment Discipline: Automatic deductions via WPS could help, but not all banks may fully enforce or adopt sophisticated repayment mechanisms right away.
- Credit Quality: If eligibility broadens significantly, banks might face pressure on credit quality, unless they maintain prudent underwriting standards.
- Education & Awareness: Low-income borrowers may still lack awareness about credit products, interest rates, and risks. Ensuring they understand loan terms will be critical.
Broader Impact
This policy change could reshape the UAE’s personal lending landscape. By lowering one of the more restrictive barriers to credit, the central bank is encouraging a more inclusive banking ecosystem. Over time, this may also support greater economic mobility, especially among the country’s working-class and younger residents.
For banks, it's a balancing act: expanding access while managing risk. Success in this reform could position the UAE as a model for how financial regulators can broaden access without compromising stability.